
2027 Tax Brackets, IRA, 401(k), and HSA Limits: What You Need to Know
Federal tax brackets for 2027, plus capital gains rates, the standard deduction, and contribution limits and tax benefits for Traditional IRA, Roth IRA, 401(k), Roth 401(k), and HSA accounts.
4 min readPublished
Tax season is simpler when you know two things: what rate you are paying on each dollar of income, and which accounts let you keep more of it. This guide covers the 2027 federal tax brackets, capital gains rates, and the four tax-advantaged accounts that most business owners and investors should know about: Traditional IRA, Roth IRA, 401(k), and HSA.
Note
What changed from 2026
The IRS adjusts most thresholds for inflation every year. For 2027, the bracket thresholds rose by about 3%:
| 2026 | 2027 | |
|---|---|---|
| Standard deduction (single) | $16,100 | $16,600 |
| Standard deduction (married filing jointly) | $32,200 | $33,200 |
| Top of the 12% bracket (single) | $50,400 | $52,025 |
| Start of the 37% bracket (single) | $640,600 | $661,375 |
| 0% long-term capital gains, up to (single) | $49,450 | $51,050 |
| HSA limit (self-only / family) | $4,400 / $8,750 | $4,500 / $9,000 |
The rates themselves are unchanged: 10%, 12%, 22%, 24%, 32%, 35%, and 37%.
2027 federal tax brackets
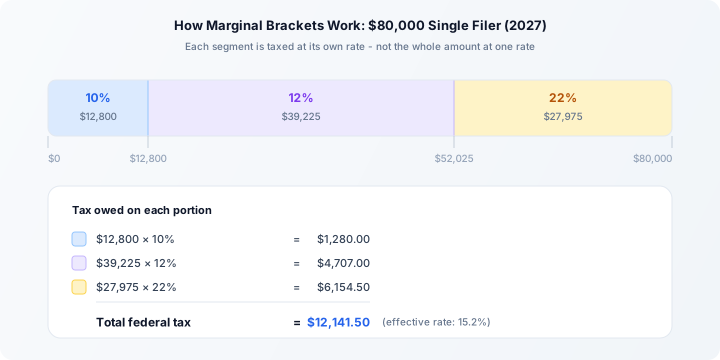
The U.S. uses a marginal tax system. You do not pay a single rate on all your income; each chunk of income is taxed at its own rate. The first dollars you earn are taxed at 10%, the next chunk at 12%, and so on. Only the income above each threshold is taxed at the higher rate.
| Rate | Single | Married Filing Jointly | Head of Household | Married Filing Separately |
|---|---|---|---|---|
| 10% | Up to $12,800 | Up to $25,600 | Up to $18,250 | Up to $12,800 |
| 12% | $12,801 - $52,025 | $25,601 - $104,050 | $18,251 - $69,650 | $12,801 - $52,025 |
| 22% | $52,026 - $109,125 | $104,051 - $218,250 | $69,651 - $109,100 | $52,026 - $109,125 |
| 24% | $109,126 - $208,325 | $218,251 - $416,650 | $109,101 - $208,300 | $109,126 - $208,325 |
| 32% | $208,326 - $264,550 | $416,651 - $529,100 | $208,301 - $264,550 | $208,326 - $264,550 |
| 35% | $264,551 - $661,375 | $529,101 - $793,650 | $264,551 - $661,350 | $264,551 - $396,825 |
| 37% | Over $661,375 | Over $793,650 | Over $661,350 | Over $396,825 |
Note
Why this matters for business owners: Tax-advantaged accounts like IRAs, 401(k)s, and HSAs reduce your taxable income, which can keep more of your earnings in a lower bracket. A $4,500 HSA contribution for someone in the 24% bracket saves $1,080 in federal tax.
2027 capital gains tax rates
When you sell an investment, the profit is a capital gain. How it's taxed depends on how long you held the asset.
Short-term gains (held one year or less) are taxed as ordinary income: the same marginal rates shown in the bracket table above.
Long-term gains (held more than one year) get preferential rates of 0%, 15%, or 20% depending on your taxable income:
| Rate | Single | Married Filing Jointly | Head of Household | Married Filing Separately |
|---|---|---|---|---|
| 0% | Up to $51,050 | Up to $102,100 | Up to $68,350 | Up to $51,050 |
| 15% | $51,051 - $563,200 | $102,101 - $633,600 | $68,351 - $598,400 | $51,051 - $316,800 |
| 20% | Over $563,200 | Over $633,600 | Over $598,400 | Over $316,800 |
These thresholds apply to your total taxable income, not just your gains. Your ordinary income fills the brackets first, then long-term gains stack on top. Two people with identical gains can pay different rates if their other income differs.
Note
Special rates: Gains on collectibles (art, coins, antiques) are taxed at a maximum rate of 28%. Unrecaptured depreciation on real property (Section 1250 gain) is taxed at a maximum rate of 25%.
Why this matters for investors: The 0% bracket is one of the most overlooked tax benefits. A married couple with $80,000 in taxable income can realize up to $22,100 in long-term gains ($102,100 − $80,000) and pay zero federal tax on those gains. Tax-loss harvesting (selling losing positions to offset gains) is another strategy to manage capital gains tax exposure.
Traditional IRA
A Traditional IRA is an individual retirement account where contributions may be tax-deductible, meaning they reduce your taxable income in the year you contribute.
2027 contribution limits
The IRS announces retirement plan limits separately from the tax brackets. The 2027 figures below are marked pending until that notice is published; the 2026 limits are shown for reference.
| 2026 | 2027 | |
|---|---|---|
| Annual limit (under 50) | $7,500 | Pending |
| Annual limit (age 50+) | $8,600 | Pending |
Is a Traditional IRA tax-deductible?
It depends on whether you (or your spouse) have a retirement plan at work:
No workplace plan: Your full contribution is deductible regardless of income.
With a workplace plan, the deduction phases out by modified AGI (MAGI):
| Situation | 2026 phase-out range | 2027 phase-out range |
|---|---|---|
| You have a workplace plan (single) | $81,000 - $91,000 | Pending |
| You have a workplace plan (married filing jointly) | $129,000 - $149,000 | Pending |
| Your spouse has a workplace plan, you don't (married filing jointly) | $242,000 - $252,000 | Pending |
Below the range you get the full deduction; inside it, a partial deduction; above it, none. The last row is a common scenario for business owners whose spouse has a 401(k) at work. The phase-out is much higher because you're not directly covered by a plan, but it still exists.
Even if your contribution is not deductible, the earnings inside the account grow tax-deferred. You do not pay taxes on gains until you withdraw in retirement.
Benefits
- Reduces taxable income now (if deductible)
- Earnings grow tax-deferred
- No income limit to contribute (unlike Roth IRA)
- Deadline: for tax year 2027 contributions
Roth IRA
A Roth IRA works in reverse: contributions are not tax-deductible, but qualified withdrawals in retirement are completely tax-free, including all the growth.
2027 contribution limits
The Roth IRA shares its limit with the Traditional IRA: you can split contributions between them, but the total across both cannot exceed the annual limit ($7,500 in 2026, or $8,600 if 50+; 2027 pending).
Income limits
Unlike Traditional IRAs, Roth IRAs have income eligibility limits. Below the range you can make a full contribution; inside it, a partial contribution; above it, none.
| Filing status | 2026 MAGI phase-out | 2027 MAGI phase-out |
|---|---|---|
| Single | $153,000 - $168,000 | Pending |
| Married filing jointly | $242,000 - $252,000 | Pending |
Note
Benefits
- Withdrawals in retirement are tax-free (contributions and earnings)
- No required minimum distributions (RMDs) during your lifetime
- Contributions (not earnings) can be withdrawn anytime without penalty
- Ideal if you expect to be in a higher tax bracket in retirement
401(k) and Roth 401(k)
A 401(k) is an employer-sponsored retirement plan with significantly higher contribution limits than IRAs. Most plans offer both a Traditional 401(k) (pre-tax contributions, taxed on withdrawal) and a Roth 401(k) (after-tax contributions, tax-free withdrawal).
2027 contribution limits
| 2026 | 2027 | |
|---|---|---|
| Employee contribution (under 50) | $24,500 | Pending |
| Catch-up (age 50+) | $8,000 | Pending |
| Catch-up (age 60-63) | $11,250 | Pending |
The standard catch-up applies to everyone 50 and older. The SECURE 2.0 Act adds a higher catch-up specifically for ages 60-63; after 63, it reverts to the standard amount.
Note
Traditional 401(k) vs. Roth 401(k)
| Traditional 401(k) | Roth 401(k) | |
|---|---|---|
| Tax on contributions | Pre-tax (reduces taxable income now) | After-tax (no deduction) |
| Tax on withdrawals | Taxed as ordinary income | Tax-free |
| Best if you expect | Lower tax bracket in retirement | Higher tax bracket in retirement |
| RMDs | Required starting at age 73 | Not required during your lifetime |
No income limits. Unlike Roth IRAs, Roth 401(k) contributions have no income phase-out: any employee can contribute regardless of how much they earn.
Benefits
- Highest contribution limits of any individual retirement account
- Employer match (if offered) is essentially free money
- Traditional: immediate tax savings through lower taxable income
- Roth: tax-free growth and withdrawals in retirement
Health Savings Account (HSA)
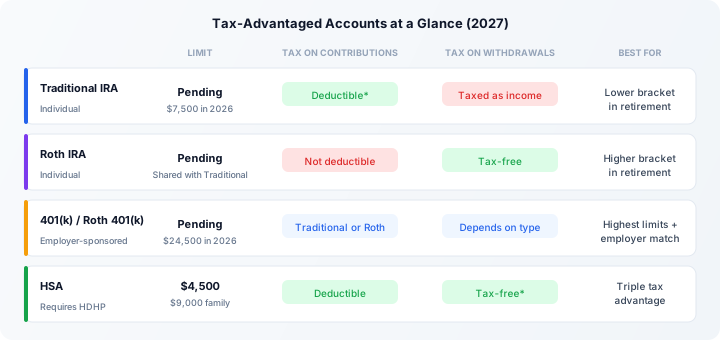
An HSA is the only account in the tax code with a triple tax advantage: contributions are tax-deductible, earnings grow tax-free, and withdrawals for qualified medical expenses are tax-free. No other account does all three.
2027 contribution limits
| Self-only | Family | |
|---|---|---|
| Annual limit | $4,500 | $9,000 |
| Age 55+ catch-up | +$1,000 | +$1,000 |
| Total (55+) | $5,500 | $10,000 |
Eligibility
You must be enrolled in a High Deductible Health Plan (HDHP) to contribute. For 2027, your HDHP must have a minimum deductible of $1,750 (self-only) or $3,500 (family), and out-of-pocket costs capped at no more than $8,700 (self-only) or $17,400 (family).
Benefits
- Triple tax advantage: deductible contributions + tax-free growth + tax-free withdrawals for medical expenses
- Unused funds roll over indefinitely (no "use it or lose it")
- After age 65, withdrawals for any purpose are penalty-free (taxed as income if not for medical expenses, similar to a Traditional IRA at that point)
- Can be invested in stocks, bonds, and mutual funds for long-term growth
- Deadline: for tax year 2027 contributions
Which accounts should you use?
The answer depends on your situation, but here are general guidelines:
- Everyone: If you have an HDHP, max out your HSA first. No other account gives you a triple tax benefit.
- Employees with a 401(k): Contribute at least enough to capture the full employer match, then decide between Traditional and Roth based on your expected future tax bracket.
- Self-employed or no 401(k): Look into a Solo 401(k) (also called an Individual 401(k)). It has the same employee limit as a regular 401(k) plus up to 25% of net self-employment income in employer contributions. If that's not an option, use a Traditional or Roth IRA. If your income is below the deduction phase-out, Traditional gives you an immediate tax break. If you expect higher income later, Roth locks in today's lower rate.
- High earners: If you exceed Roth IRA income limits, consider the backdoor Roth strategy or maximize Roth 401(k) contributions (no income limit).
Key takeaway
Tax brackets determine how much you owe. Tax-advantaged accounts determine how much of your income is even subject to those brackets. A self-employed business owner in the 24% bracket who puts $4,500 into an HSA saves $1,080 in federal tax, and every dollar of Solo 401(k) deferral up to the 2027 limit saves another 24 cents. The contribution deadlines for IRAs and HSAs are , so plan ahead for tax year 2027.
Related
- 2026 tax brackets, IRA, 401(k), and HSA limits: last year's figures, for the return you file in 2027
- Federal Tax Liability Estimator: plug in your wages and capital gains to see your 2026 federal tax, with bracket-by-bracket detail
- The Augusta Rule: rent your home to your business tax-free: another tax strategy for business owners
References
- IRS: Tax inflation adjustments for 2027 (Rev. Proc. 2026-35): official brackets, capital gains thresholds, and standard deduction
- IRS: 2027 HSA limits (Rev. Proc. 2026-24): HSA contribution limits and HDHP requirements
- IRS Publication 969: Health Savings Accounts: HSA rules and eligibility
Disclaimer
This article is for informational purposes only and does not constitute tax, financial, or investment advice. Tax laws change frequently. Consult a qualified CPA or tax advisor for guidance specific to your situation.
Try it in Sedna
See this in action in the app. Open in app